Savings bonds have long occupied a dependable, if somewhat unremarkable, position in American personal finance. Backed by the federal government, they offer a predictable means of accumulating interest without exposure to ordinary stock market fluctuations.
Their tax treatment, however, deserves more attention than it typically receives. State and local income taxes do not apply, and certain educational expenses may qualify for an additional federal tax benefit.
An important distinction follows. Postponing a tax obligation does not eliminate it. Two principal savings bond programs are available:
Bonds issued since May 2005 earn a fixed interest rate and carry a Treasury guarantee that they will double in value after 20 years.
Interest consists of a fixed rate established at issuance and an inflation-adjusted component that changes every six months.
Both types can accumulate interest for as long as 30 years.
Taxpayers must eventually account for that interest, and the timing of recognition can have significant financial consequences.
When Do You Pay Taxes on Savings Bonds?
Timing is one of the most consequential aspects of savings bond taxation.
Unlike ordinary bank interest, which is generally taxable as it is credited, savings bond interest can accumulate for decades before federal income tax becomes payable.
IRS rules establish when accumulated interest must be recognized, while the taxpayer’s chosen reporting method determines how that income is accounted for during the bond’s lifetime.
IRS Tax Reporting Rules
Federal income tax on savings bond interest generally becomes payable when the bond is redeemed, reaches final maturity, or is otherwise disposed of in a taxable transaction, provided the interest has not already been reported.
For Series EE and Series I bonds, final maturity occurs after 30 years.
Interest stops accumulating at that point, and any previously unreported earnings generally become taxable during the year of maturity, even if the owner does not redeem the bond.
Consider a Series EE bond purchased in 1996.
Having reached final maturity in 2026, its accumulated interest generally must be included in the owner’s 2026 federal taxable income if annual reporting was not previously elected. Redemption restrictions also influence the timing of income recognition.
Owners of old bonds should therefore check their maturity dates carefully, as accumulated interest may already be taxable even if the bonds have never been redeemed.
Annual Reporting vs. Tax Deferral
IRS rules permit two principal methods of reporting savings bond interest. Annual reporting allows taxpayers to report the annual increase in a bond’s redemption value as taxable interest.
Rather than recognizing years of accumulated earnings simultaneously, the taxpayer includes smaller amounts in successive tax years.
Deferred reporting allows interest to accumulate without annual federal income tax recognition. Accumulated interest is generally reported when the bond is redeemed or reaches final maturity.
Most individual investors use deferred reporting because it postpones taxation and allows the earnings to accumulate without an annual federal income tax payment on that interest. However, deferral can create a larger taxable amount later.
A taxpayer redeeming several bonds after 25 years could recognize substantial interest in a single tax year.
Depending on other income, some of those earnings might fall within a higher marginal income tax bracket.
How to Report Savings Bond Interest to the IRS
Savings bond interest is reported as taxable interest income on a federal income tax return.
Reporting requirements depend on the amount received, the taxpayer’s accounting method, and other investment income.
| IRS Form | Purpose |
|---|---|
| Form 1099-INT | Reports interest associated with redeemed or matured savings bonds |
| Form 1040 or 1040-SR | Includes taxable savings bond interest in federal income |
| Schedule B | Provides detailed interest reporting when required |
TreasuryDirect or the financial institution handling redemption generally issues Form 1099-INT when reportable interest reaches $10.
Receiving no form does not automatically eliminate the obligation to report taxable interest.
Schedule B is generally required when total taxable interest exceeds $1,500, although additional filing conditions can require it at lower amounts.
Taxpayers reporting $1,500 or less in taxable interest who do not meet another Schedule B filing condition can ordinarily enter the amount directly on Form 1040 or 1040-SR.
Only the interest is taxable, not the original investment.
| Item | Amount |
|---|---|
| Original bond purchase | $5,000 |
| Redemption value | $8,000 |
| Taxable interest | $3,000 |
| Assumed federal marginal tax rate | 22% |
| Additional federal income tax | $660 |
Assuming the entire $3,000 is taxed at 22%, the additional federal income tax would be $660.
Actual liability may differ if part of the interest falls within another tax bracket or affects other income-based tax calculations.
Another complication concerns interest reported in earlier years. Form 1099-INT may include accumulated interest that a taxpayer previously reported under the annual reporting method. Maintaining records of earlier interest declarations is therefore essential.
Federal, State, and Local Tax Treatment
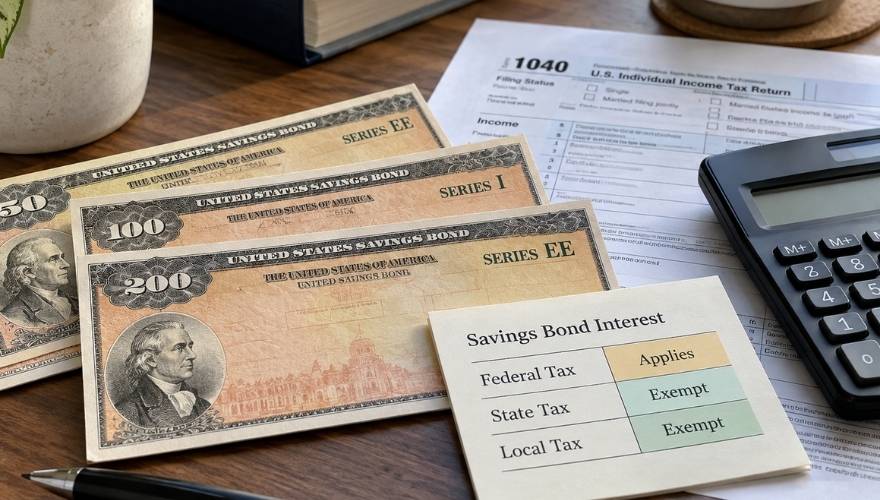
Savings bond interest receives substantially different treatment under federal and state income tax systems.
At the federal level, interest is generally taxed as ordinary income. Preferential long-term capital gains rates do not apply simply because the investment has been held for several decades.
Applicable federal tax rates depend on the taxpayer’s ordinary income tax bracket during the year of recognition.
State and local income tax treatment is considerably more favorable. Interest earned on U.S. savings bonds is exempt from state and local income taxes. Unlike federal deferral, this exemption is permanent and does not depend on the bond’s holding period.
Consider $1,000 in interest earned by an investor residing in a state with a hypothetical 5% income tax rate.
| Investment income | State income tax |
|---|---|
| $1,000 in taxable bank interest | $50 |
| $1,000 in savings bond interest | $0 |
| Potential state tax savings | $50 |
Actual savings depend on applicable state tax rules and the investor’s circumstances.
For residents of states with relatively high income tax rates, the exemption can improve the after-tax return compared with otherwise similar taxable investments.
Nevertheless, state tax savings should not be confused with federal income tax relief.
Federal taxation generally still applies, although recognizing the interest may be postponed.
Can Savings Bond Interest Be Tax-Free for Education?
An additional federal income tax benefit exists under the Education Savings Bond Program.
Qualifying investors may exclude some or all savings bond interest when eligible proceeds are used to pay qualified higher education expenses during the same tax year as redemption.
Eligible investments include Series EE bonds issued after 1989 and Series I bonds. Qualification depends on several conditions:
| Requirement | IRS Rules |
|---|---|
| Bond ownership | Bonds must generally be registered in the taxpayer’s name, individually or jointly with a spouse. |
| Age requirement | Bond owner must have been at least 24 years old before the bond’s issue date. |
| Qualified education expenses | Tuition and required fees at eligible higher education institutions for the taxpayer, spouse, or dependent. |
| Filing status | Married taxpayers filing separately are not eligible for the exclusion. |
| Income limits | Modified adjusted gross income must fall within the applicable IRS eligibility limits. |
Educational expenses used for certain other tax benefits or covered by tax-free assistance must also be accounted for when calculating the exclusion.
Income Limits for the Education Exclusion
Income restrictions substantially narrow the availability of this benefit.
For the 2025 tax year, the Education Savings Bond Program applies the following modified adjusted gross income thresholds.
| Filing status | Phaseout begins | Fully phased out |
|---|---|---|
| Married filing jointly | $149,250 | $179,250 |
| Single, head of household, or qualifying surviving spouse | $99,500 | $114,500 |
Taxpayers whose modified adjusted gross income falls within these ranges receive a reduced exclusion.
Once income reaches the upper threshold, the exclusion is unavailable.
Thresholds are adjusted periodically, making it necessary to consult the figures applicable to the year of redemption.
Eligible taxpayers calculate the exclusion using IRS Form 8815.
Importantly, spending part of the redemption proceeds on qualifying education expenses does not automatically exclude all accumulated interest.
Suppose a taxpayer redeems a qualifying bond for $9,000, consisting of $6,000 in principal and $3,000 in interest.
If adjusted qualifying educational expenses total $7,650, the preliminary interest exclusion is calculated as follows:
$7,650$9,000
= $2,550
Assuming all other eligibility requirements are satisfied and no income-based phaseout applies, $2,550 in interest could be excluded. Another $450 would be taxable.
Education exclusions therefore require more than directing the money toward college expenses. Income, ownership, age, and eligible spending all determine the result.
Tax Deferral Is Not Tax Exemption
U.S. savings bonds offer three distinct potential tax advantages: federal income tax deferral, exemption from state and local income taxes, and a conditional federal exclusion for qualifying educational expenses.
Both operate under different rules.
Federal deferral postpones the recognition of interest, ordinarily until redemption or final maturity. State and local income tax exemptions eliminate those particular liabilities.
Educational exclusions may eliminate some or all federal income tax on qualifying interest, but only when specific requirements are satisfied.