Property tax assessments are government estimates, and government estimates are not always correct. Unfortunately, an error in a property’s valuation can become a recurring expense for homeowners who fail to notice it.
Incorrect square footage, outdated records, overlooked structural damage, or poorly selected comparable properties can all result in excessive assessments.
Still, a higher property tax bill does not necessarily indicate an inaccurate valuation. Changes in local tax rates, exemptions, and assessment rules can increase what homeowners owe even when the assessed value is correct.
Experience with public finance teaches a useful distinction: A tax can be calculated correctly using an incorrect valuation.
Homeowners who decide to appeal property tax assessment figures must demonstrate that the government’s estimate is inaccurate, rather than simply argue that their taxes have become excessive.
Successful challenges require credible evidence, compliance with local procedures, and a reasonable expectation of financial savings.
How Property Tax Assessments Affect Your Bill
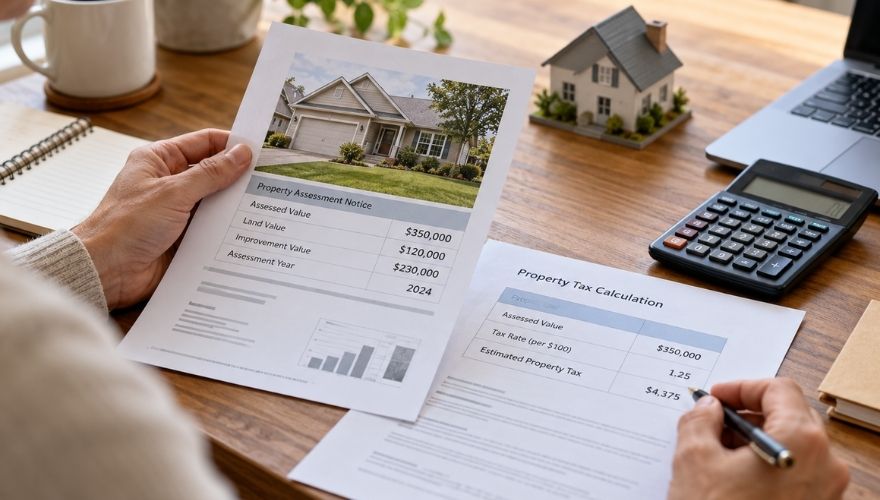
Local assessors estimate property values using location, square footage, condition, comparable sales, and improvements.
According to the International Association of Assessing Officers, assessed value is used to determine a property’s share of the local tax burden. Assessors establish valuations, while applicable tax rates and other legal provisions determine the amount owed. Not every jurisdiction assesses property at full market value.
Consider a jurisdiction applying an 80% assessment ratio. A property valued at $100,000 would carry an assessed value of $80,000.
Reassessment schedules also vary. Some jurisdictions conduct annual reassessments, while others update valuations every two years or less frequently.
A simplified calculation demonstrates the financial consequences of correcting an excessive taxable value.
| Tax Calculation | Original | Corrected |
|---|---|---|
| Taxable value | $300,000 | $270,000 |
| Property tax rate | 1.5% | 1.5% |
| Annual property tax | $4,500 | $4,050 |
| Annual savings | $450 |
When You Have Good Reasons to Appeal
A defensible challenge identifies a measurable valuation problem rather than dissatisfaction with the resulting bill.
Several circumstances warrant investigation:
| Reason | Supporting Evidence |
|---|---|
| Incorrect property details | Errors in square footage, rooms, or improvements |
| Excessive valuation | Comparable properties selling at lower prices |
| Unequal assessment | Similar properties carrying significantly different assessments |
| Property damage | Foundation cracks, roof deterioration, or basement flooding |
| Incorrect classification | A single-family home incorrectly listed as multifamily |
Consider a house recorded at 2,000 square feet when its actual area is 1,800 square feet. Correcting that 200-square-foot discrepancy could reduce the property’s valuation, depending on the assessment method. Another example involves comparable homes selling for $300,000 while the assessor values a property at $350,000.
That represents a 16.7% valuation premium relative to the comparable sale prices. Differences in property condition, location, and improvements must still be considered.
State authorities recognize such disputes. The Texas Comptroller’s official guidance permits homeowners to contest inaccurate appraised values and errors in property records.
Neighborhood price declines can also support a challenge when relevant sales occurred before the applicable valuation date.
Lower assessments on neighboring homes, however, are not conclusive evidence of unequal treatment. Assessment caps, exemptions, and structural differences can explain the disparity.
How to Appeal Your Property Tax Assessment
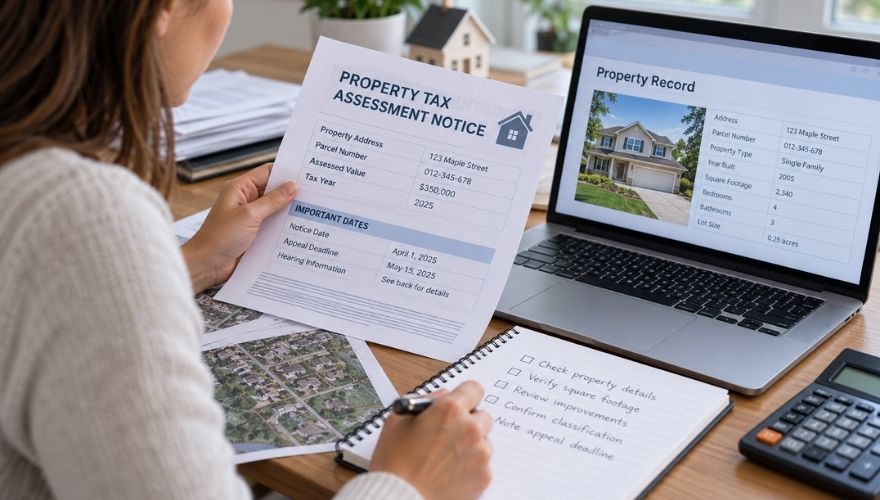
A successful property tax assessment appeal process generally involves five steps, although individual jurisdictions establish their own requirements.
1. Check the assessment notice and deadline.
Review the assessed value, official valuation date, filing instructions, and property tax appeal deadline.
Filing windows vary considerably. In Texas, for example, state rules generally require homeowners to file by May 15 or within 30 days after the appraisal district mails its notice, whichever is later.
Missing the prescribed deadline can restrict the available remedies.
2. Examine the assessor’s property records.
Verify square footage, bedrooms, bathrooms, additions, renovations, and property classification.
Clerical mistakes may sometimes be corrected informally. However, an informal discussion should not be assumed to extend the filing deadline.
3. Collect comparable sales and documentation.
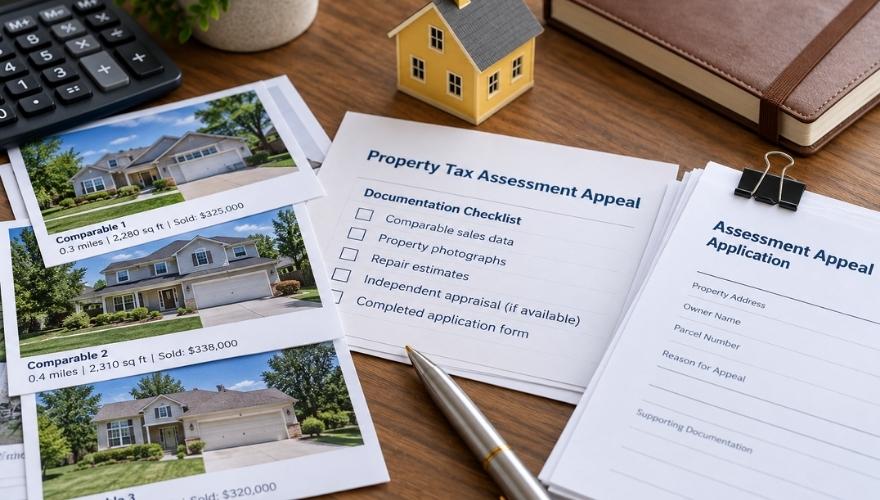
Look for similar properties within approximately half a mile, preferably with square footage within 10% to 15% of the subject property.
Those distances and size ranges are practical screening guidelines, not universal legal requirements.
Compare recent sales within the relevant valuation period and gather photographs, repair estimates, or independent appraisals where appropriate.
4. Submit the required documentation.
Complete the official forms, attach supporting evidence, and retain confirmation of submission.
Some jurisdictions offer informal reviews before hearings, while others require presentation before an assessment review board.
Formal proceedings may require more than submitting a completed application. Under New York’s assessment grievance procedures, a review board can require a property owner or authorized representative to appear and provide additional evidence.
Refusing to answer material questions can prevent the requested reduction.
5. Examine the decision and further options.
An unfavorable decision does not necessarily conclude the matter.
For example, New York’s Small Claims Assessment Review program allows qualifying property owners to request additional review, generally after completing the administrative review procedure. Its filing fee is $30.
Depending on local law, a valuation review can also reveal previously unrecorded improvements or other evidence supporting a higher assessment.
When Is Appealing Worth the Cost?
Homeowners should investigate assessments appearing to exceed market value by 10% or more.
However, that figure is a practical screening benchmark, not a universal legal threshold.
An independent appraisal may strengthen complicated cases, although professional fees can exceed several hundred dollars.
Before deciding to appeal property tax assessment figures, homeowners should compare potential savings against filing costs, professional expenses, and the likelihood of success.
| Annual Tax Savings | Challenge Costs | First-Year Net Benefit |
|---|---|---|
| $150 | $300 | -$150 |
| $450 | $300 | $150 |
| $1,200 | $500 | $700 |
Professional assistance may be justified for commercial properties, unusually valuable homes, disputed classifications, or complicated legal proceedings.
Straightforward factual errors, however, may justify a self-filed challenge even when potential savings are modest.
Another consideration is how long the correction will affect future bills. Annual savings of $450 sustained for three years would produce $1,350 before expenses, assuming unchanged taxable values and tax rates.
Yet expected savings should account for uncertainty.
A 50% estimated probability of obtaining $450 in annual savings produces an expected first-year benefit of $225 before expenses.
Spending $300 to pursue that result would be difficult to justify on first-year economics alone.
Closing Thoughts
Property tax assessments are administrative estimates, not infallible judgments.
Homeowners have good reason to question valuations that contradict reliable sales evidence, contain factual errors, or overlook significant property damage.
Nevertheless, the question is it worth appealing property taxes cannot be answered by examining the tax bill alone.
Potential savings must justify the expenses, uncertainty, and procedural requirements involved.
Careful examination of official property records and comparable sales is generally the sensible starting point. Correcting an inaccurate assessment can prevent unnecessary taxation, provided the cost of securing that correction does not consume the resulting savings.